Clarity for stakeholders
The report presents material impacts and their management in balanced language that helps customers, employees, financiers and communities understand performance.
We help organisations and companies build an annual sustainability report that starts with material impacts and stakeholders, moves through governed data and management review, and finishes with balanced content and a GRI index that leads readers clearly to disclosures and evidence. For companies with securities listed on the Egyptian Exchange, we add a structured pathway aligning report and data with relevant ESG and climate-related disclosures.
We design reporting as an annual management cycle connecting impacts, responsibilities, indicators and review—not as a writing exercise that starts close to publication.
The report presents material impacts and their management in balanced language that helps customers, employees, financiers and communities understand performance.
Every disclosure has a source, owner, quality control and approval route, improving traceability and reducing last-minute review cycles.
A structured report provides a practical reference for sustainability and ESG requirements in prequalification, bids and customer requests.
Gaps and trends become inputs for targets, initiatives and the next reporting cycle rather than disappearing after publication.
We bring sustainability reporting and ESG and climate-related disclosures into one data and review cycle, helping finance, sustainability, governance and board teams work from an organised and traceable source.
Review listing status, reporting year, included entities, calendar, required attachments and team responsibilities before data collection begins.
Create a data dictionary, indicator ownership, quality controls and evidence pathways for environmental, social, governance and climate-related financial disclosures.
Align report content, disclosure matrix and internal reviews with the annual report and governance-body comments, supported by an organised review file.
We establish one route from reporting boundaries and material topics through data, drafting and approval, with gaps and assumptions made transparent.
Drafting begins near the deadline without a calendar, disclosure owners or defined approval gates.
It is unclear whether subsidiaries, locations, operations or value-chain activities are included, making data difficult to compare.
Topics are selected from a generic list or survey alone, without structured assessment of the most significant impacts on the economy, environment and people, including human rights.
Definitions, periods, units and sources vary, while estimates, restatements and quality controls are not documented.
Positive messages go beyond actual results and boundaries, increasing the risk of unsupported claims.
References do not lead users to disclosures, or omissions, the statement of use and applied Standards are not presented appropriately.
The scope adapts to a first or repeat report, number of entities and sectors, data maturity, and whether reporting is in accordance with or with reference to the GRI Standards.
Confirm the objective, audience, boundaries and suitable application route before content collection.
Determine the organisation’s most significant impacts through a documented, sector-relevant process.
Translate applied Standards into traceable, reviewable information requests.
Build a balanced narrative connecting policies, action, results and boundaries with evidence.
Manage approval and assurance readiness, then retain learning for the next cycle.
Design, translation and external assurance levels are agreed separately, while preparation maintains traceability and consistency throughout.
Set the audience, period, entities, route, deadline, reporting team and approval authority.
Review reports, policies, systems and data and establish gaps and the work plan.
Assess impacts, engage stakeholders, apply relevant Sector Standards and document priority decisions.
Issue disclosure templates, brief owners and track submissions, gaps and assumptions.
Check consistency and quality, analyse performance and trends, and draft balanced, supportable content.
Coordinate management and governance review, close comments and prepare evidence for an independent assurance provider when requested.
Complete the GRI index, statement of use, applicable disclosures and annual-report integration, then retain data gaps and the annual improvement plan.
Establish boundaries, materiality, data, content and index from the starting point.
A recurring programme with dates, owners, reviews and year-on-year improvement.
Review context, impacts, stakeholders and material topics and document changes.
Review applicability, ESG and climate indicator matrix, data, internal reviews and annual-report integration within the agreed scope.
A focused plan to prioritise feasible data, content and approvals within a defined time without going beyond available evidence.
Specialist environmental, social and governance inputs can be integrated from qualified technical providers, with external assurance and report production coordinated through independent, fit-for-purpose parties.
We support the company in organising ESG and climate disclosure data and content against current requirements and its internal approval route, without implying that we represent the Financial Regulatory Authority or Egyptian Exchange or have authority to accept disclosures.
View the official disclosure pageWe prepare data and evidence pathways for an independent assurance provider when requested and work with design and translation specialists to produce a clear report without compromising assurance independence.
Check the latest GRI StandardsRelated founder experience in complex sectors is presented at a high level; these cases are not represented as delivered GRI reports unless explicitly stated.

Environmental performance and compliance work across industrial-area settings associated with MODON.
View experience →
Systematic environmental oversight aligned with national and international requirements.
View experience →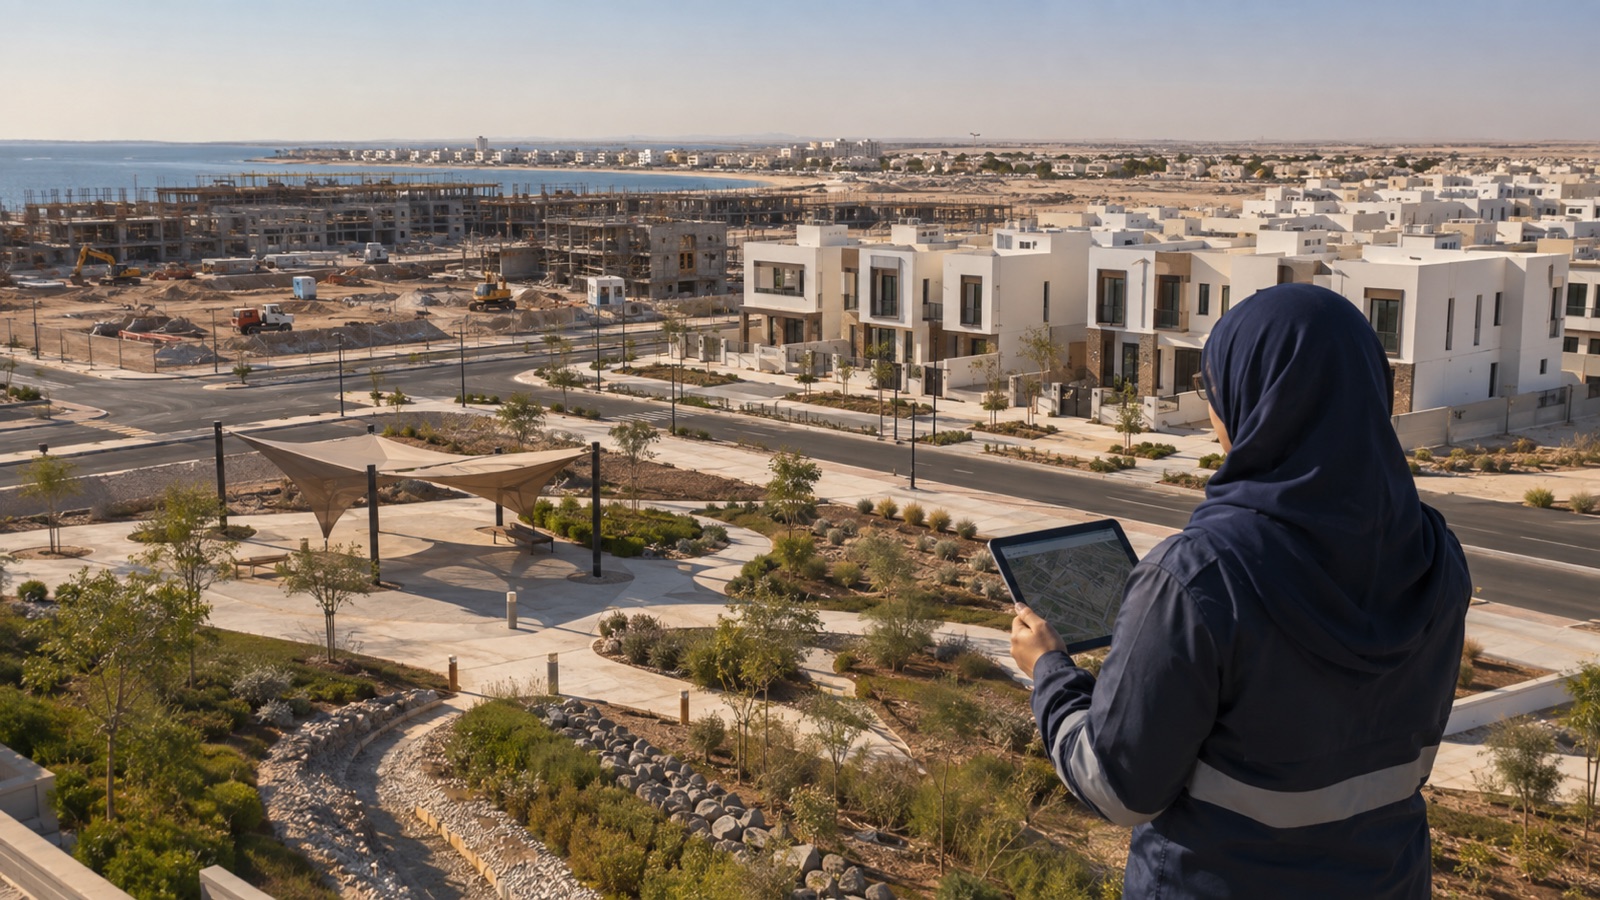
Environmental support for municipal and housing developments in Obhur, Jeddah and Al Shifa, Riyadh.
View experience →An in-accordance claim requires the organisation to comply with all requirements for that route in GRI 1. A with-reference claim supports selected disclosures when that route’s requirements are met. We select the route after readiness assessment and do not promise a claim before review is complete.
GRI 1, GRI 2 and GRI 3 are used together with applicable Sector Standards and the Topic Standards linked to the material-topic list. Current effective versions are confirmed at the start of every cycle.
We analyse organisational context, activities and business relationships; identify actual and potential positive and negative impacts; draw on stakeholders and experts; then prioritise the most significant impacts and document the method and decisions.
Yes, after determining what can be supported reliably. Boundaries, estimates and permitted omissions are made transparent, and a data-improvement roadmap is created instead of filling gaps with unsupported claims.
A clear approval route is established for disclosure owners, executive management and the appropriate governance body. GRI also requires reporting whether the highest governance body reviews and approves the reported information, including material topics.
GRI recommends external assurance to strengthen credibility, but it is not itself required for reporting in accordance. When requested, assurance should be delivered by a competent independent provider, with scope, standard, level and limitations clearly described.
Yes. We provide a structured pathway for companies with securities listed on the Egyptian Exchange, connecting the sustainability report and ESG and climate data with the reporting calendar, internal review and annual report. Applicability, form and deadlines are confirmed each cycle; we do not provide legal advice, represent the FRA or EGX, or guarantee disclosure acceptance.
Effective Standards are checked at each cycle. Reports published in 2026 need to use GRI 101: Biodiversity 2024 instead of GRI 304, while we prepare for GRI 102: Climate Change and GRI 103: Energy, effective for reporting from January 2027, or earlier adoption if the organisation chooses.
Yes. An Arabic, English or bilingual report can be prepared with a terminology register and consistency review across numbers, tables and references.
They depend on entity and sector count, topics, stakeholders, data maturity, languages, design level and requested assurance. A clear programme, scope and fee follow the readiness review.
Share the reporting period, entities, sector, available data and publication date, and we will suggest the right readiness route and programme.